
Bona Fide Residence vs Physical Presence Test: Which One Qualifies You for the FEIE?
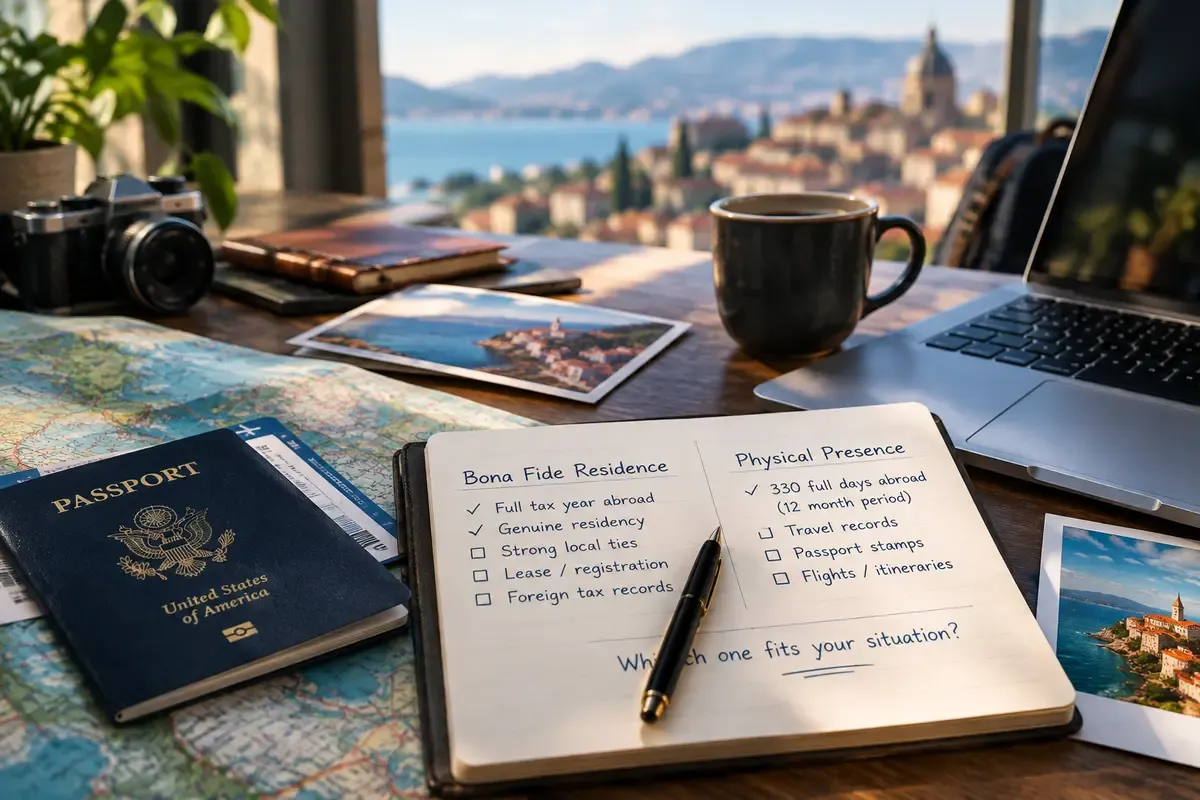
A missionary couple who had just relocated to the Philippines once found themselves on a video call with Jorge Rivas, EA, convinced they could not touch the Foreign Earned Income Exclusion until they had lived overseas a full year. That worry eases once someone realizes the FEIE has two separate qualification paths, and the Physical Presence Test does not require completing a full tax year abroad before someone can qualify. The Bona Fide Residence Test and the Physical Presence Test are the two paths to FEIE qualification, and which one applies depends on how long someone has been abroad and how their time there is structured.
Why the IRS Requires Proof of Living Abroad
Citizenship based taxation means the IRS expects a return from every American citizen and green card holder, no matter where income was earned. What changes the outcome is whether the taxpayer can prove, under IRS terms, that they actually live abroad rather than simply working remotely from a foreign address. Neither test applies on its own. It has to be established using Form 2555, and the supporting facts differ between the two tests.
What Counts as a Qualifying Tax Home
Both tests share a requirement that trips people up before the day counting or residency question even applies: a qualifying tax home outside the United States. A tax home is generally the location of someone's main place of business, employment, or post of duty. It is different from a family home or legal residence. For FEIE purposes, the IRS also considers where a person's abode is located, including their closer family, economic, and personal ties, and someone who works abroad temporarily while keeping those closer ties in the United States can fail this piece even after hitting 330 days, which Jorge checks before either test enters the conversation.
What Income Actually Qualifies for the Exclusion
Not every dollar earned abroad is eligible. The FEIE applies only to foreign earned income, meaning wages, salary, and self employment income for services actually performed abroad. Passive income does not qualify, so rental income, dividends, interest, and capital gains remain fully taxable regardless of which test someone passes. This distinction can be especially important for expat business owners. Business income does not automatically become foreign earned income simply because the owner lives abroad, and the treatment can depend on how the income is generated and whether amounts represent compensation for personal services or a distribution of business profits.
The Physical Presence Test Measures Days, Not Intent
This test is arithmetic. It requires 330 full days physically outside the United States within any twelve month period, which does not need to match the calendar year. This 330 day rule for expats lets someone who moved abroad in April count from their actual arrival date instead of waiting for January. The days do not need to be spent in one country either, so time split between Malaysia, Thailand, and a short trip through Australia all counts, as long as none of it happens on US soil.
Because this test does not weigh intent, a funeral, a wedding, or a last minute work trip home can quietly cut into the total, with no exception for the reason behind the trip. Jorge sees this catch international school teachers most often, since summer travel home is common in that profession and rarely gets tracked against the qualifying window until too late to fix.
The Bona Fide Residence Test Looks at How Someone Actually Lives
Instead of counting days, this test asks whether the taxpayer has genuinely built a life abroad for an uninterrupted period that includes one full tax year. The IRS looks at the facts and circumstances of someone's life abroad, including their intention and purpose for living there, their activities, their family arrangements, and whether they are treated as a resident for foreign tax purposes. Documents such as leases, local registration, and foreign tax records can help support those facts, though none of them alone determines the outcome.
The advantage is flexibility around travel. Short trips back to the United States generally do not break qualification here, as long as intent to return abroad stays clear and local ties remain intact. Meeting the IRS bona fide residence requirements is ultimately about consistency between someone's stated intent and how their life abroad actually looks, not any single document. This test tends to fit missionaries better than Physical Presence, since periodic support raising trips would otherwise chip away at a strict day count in a way Bona Fide Residence does not penalize.
A Waiver Most Expat Tax Content Never Mentions
One detail that rarely shows up in generic explainers is the foreign country waiver under Internal Revenue Code section 911(d)(4). If a taxpayer had to leave a country early because of war, civil unrest, or a similarly disruptive condition, the IRS can waive the minimum time requirement, provided the taxpayer can show they would have otherwise qualified. The IRS publishes qualifying countries and periods each year through official guidance, so anyone affected by a sudden evacuation should confirm coverage rather than assume the exclusion is lost.
Comparing the Two Tests Side by Side
Factor | Physical Presence Test | Bona Fide Residence Test |
Core requirement | 330 full days abroad in any 12 month period | Uninterrupted bona fide residence that includes an entire tax year |
What it measures | Physical days abroad | Facts, circumstances, ties, and intent |
Trips back to the US | US days count against the 330 day total | Brief trips generally may not break residence if intent to return remains |
How soon someone can qualify | Potentially during the year once the qualifying period is established | Generally requires an uninterrupted period including an entire tax year |
Typical planning fit | People whose travel history can support the day count | People with an established life and residence abroad |
Supporting evidence | Travel records, passport records, flight records | Leases, registration, foreign tax records, and other evidence of residence |
Choosing Between the Two, Combining Benefits, and Common Blind Spots
Some expats genuinely meet both tests, and the decision comes down to how their life actually functions. Someone with regular return trips to a US office may find Bona Fide Residence more workable, since occasional travel does not affect it in exactly the same way as the strict Physical Presence day count. Someone on a two year assignment often finds Physical Presence simpler, since it does not require proving a long term commitment not yet made.
The FEIE and Foreign Tax Credit are not mutually exclusive. A taxpayer may use both benefits on the same return when circumstances allow it, for example using the FEIE for qualifying income within the exclusion limit and the Foreign Tax Credit for otherwise eligible foreign income that remains taxable in the United States. The same income cannot receive both benefits. Married couples should also know each spouse has to independently meet one of the two tests, since one spouse can qualify under Bona Fide Residence while the other only qualifies under Physical Presence, or in some years does not qualify at all.
One mistake Jorge corrects often: the FEIE is not automatic. If someone wants to claim the exclusion, they generally must affirmatively elect it by attaching Form 2555 to their Form 1040 or amended return.
What Happens if Neither Test Applies Yet
This is common in the first several months abroad, before either test has had time to apply. If 330 days have not been reached and the required bona fide residence period has not been established, someone generally will not qualify under either test for that particular year, unless a specific exception such as the foreign country waiver described above applies. The Foreign Tax Credit often fills the gap, crediting US tax owed against foreign tax already paid, though it works better in high tax countries than in places with little local income tax.
Form 2350 offers another option: a filing extension tied to the date someone expects to meet one of the two tests. If a move happened partway through the year and the normal deadline lands before the qualifying period is complete, this extension avoids a rushed filing followed by an amended return. Form 2350 extends the time to file, not the time to pay, and any tax due by the regular payment deadline can still accrue interest and potentially penalties.
Why This Choice Is Not Permanent
Electing the FEIE is a choice, not a default, and it carries a consequence that catches even experienced filers off guard. Once revoked, the same exclusion generally cannot be elected again within the next five tax years without IRS approval. This matters for anyone whose income grows large enough that the Foreign Tax Credit starts beating the exclusion, a long term planning decision worth reviewing before filing rather than after.
How Jorge Rivas, EA Determines the Right Test
As a federally licensed Enrolled Agent focused exclusively on international tax, Jorge works through this exact question with clients across more than fifteen countries every filing season. Proving foreign residency to the IRS usually comes down to matching specific dates against the right documentation, and guessing wrong can mean missing an exclusion that was available all along. The process runs entirely remotely: travel history and residency documents get uploaded through a secure portal, details get reviewed on a video call, and Jorge confirms which test applies before anything gets filed. Clients checking in from Dubai, Manila, and Toronto all go through the same process.
Schedule a Free Consultation
Anyone unsure where they stand can get that answered directly through a free fifteen minute consultation focused on the relevant dates and which test fits with the least risk of disqualification. Reach the office at (803) 467 5815 or (843) 353 0571, by email at Jorge.Rivas@RatliffCPAFirm.com, or through the contact page to get started.
Frequently Asked Questions
Can the qualifying test change from one year to the next?+
Yes. Many expats qualify under Physical Presence during the first year abroad and shift to Bona Fide Residence once local ties are more established.
Does one trip home ruin the Physical Presence Test for the whole year?+
Not automatically, but time spent back in the United States subtracts directly from the day count, so enough trips home can push the qualifying period later than planned.
Is a specific visa required for Bona Fide Residence?+
No single visa is required, though legal immigration status abroad is one factor the IRS weighs when deciding whether residency is genuine.
What happens if someone falls just short of 330 days?+
Falling even one day short means that the test is not met for that window, which is why tracking travel carefully matters more than most new expats assume.
Do government employees or contractors qualify the same way?+
Employees of the US government generally cannot exclude their government wages under the FEIE. Contractors are different and depend on the applicable facts and rules, so confirming the specific employment category matters first.
Does the FEIE reduce self employment tax too?+
No. The exclusion can lower income tax on self employment earnings, but self employment tax itself is calculated separately.
What records should be kept to support either test?+
Examples of supporting records include flight confirmations and passport records for the Physical Presence Test, and leases, local registration, foreign tax records, and other evidence of an established life abroad for the Bona Fide Residence Test.
Let's Run Your Numbers
The only way to know which is better for you is to model both. Book a free consultation and I'll show you the difference for your country and income.
Schedule Free Consultation →- Jorge I. Rivas, EA
- (803) 467-5815
- Jorge.Rivas@RatliffCPAFirm.com
Related Articles
Late FBAR? How to write a reasonable cause statement
Missed an FBAR? With the Delinquent FBAR procedures gone, a reasonable cause statement carries a late filing. What it must show, an example, and what to avoid.
Does the US–Chile Tax Treaty Change Anything for Americans in Chile?
The US–Chile tax treaty has been in force since December 2023, yet US citizens still file a US return. Here is what it actually changes, and what it does not.
Retiring in Ecuador? US Taxes, IESS, and What the IRS Expects
Dollarization makes Ecuador easy to live in, but not to forget about the IRS. Here is how Ecuador taxes residents, where IESS fits, and what US retirees still have to file.