
Is Foreign Pension Income Taxable in the US? What Expats Need to Know
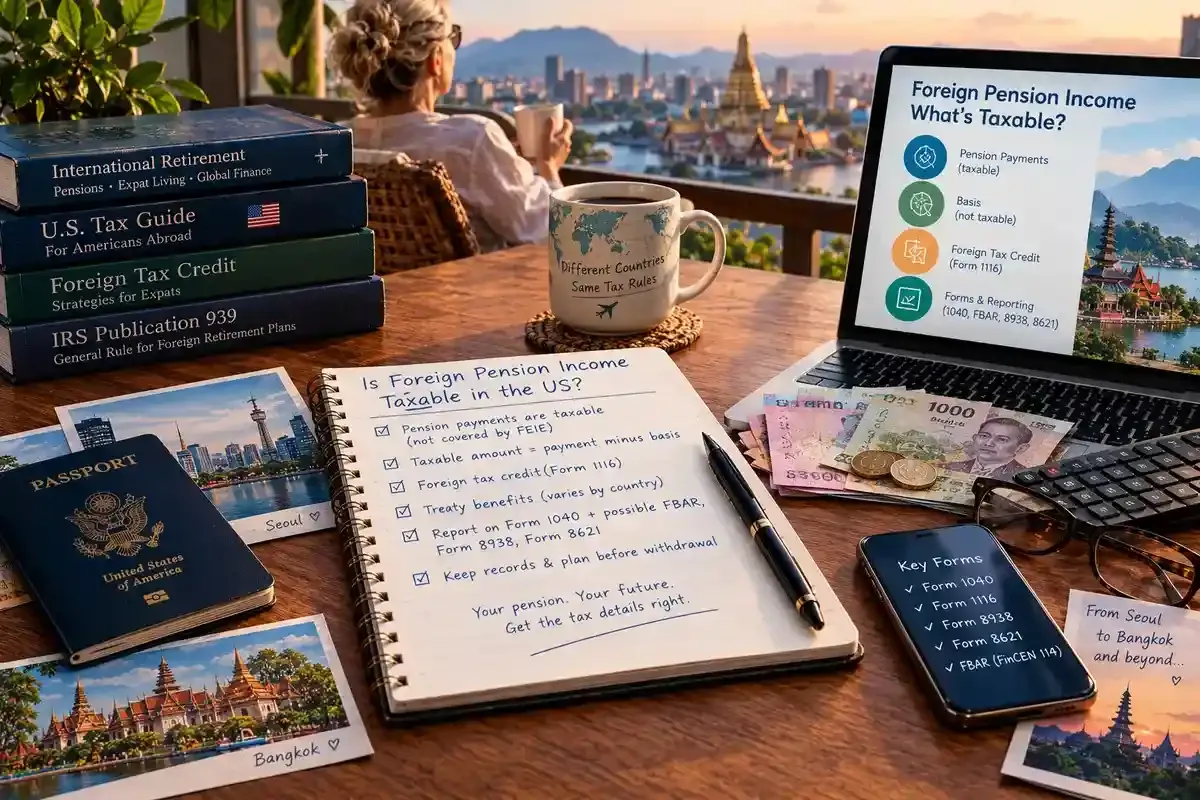
Picture a teacher who spent eleven years at international schools in Seoul and Bangkok. Her school retirement fund is finally paying out, and with it comes a question she never expected to worry about: will the IRS take a share of money earned and saved overseas, and was something missed along the way?
The short answer from Jorge Rivas, EA is yes. For US citizens and green card holders, the rules that make foreign pension income taxable in the US apply no matter which country pays it, and the Foreign Earned Income Exclusion does not cover it. What is actually owed depends on three things: basis in the plan, foreign tax already paid, and any tax treaty with the paying country.
How the IRS Taxes a Foreign Pension
Pensions Are Not Covered by the FEIE
Section 911 of the tax code states that foreign earned income does not include amounts received as a pension or annuity, and the Form 2555 instructions repeat the same rule. That holds even when the pension was built entirely from years of overseas work.
Only the Amount Above Your Basis Is Taxed
The taxable amount is generally the payment minus your "investment in the contract," the IRS term for basis. Basis is money that went into the plan after US tax was already paid on it, and that part comes back tax free. Employer money and investment growth that were never taxed are usually taxable when paid out.
Most foreign plans are nonqualified for US purposes, and IRS Publication 939 says payments from nonqualified plans use the General Rule, which spreads basis evenly across the payments you are expected to receive.
This is often the moment the paperwork starts to feel personal. No US tax form arrives from a foreign plan, so the numbers depend on records kept years ago, sometimes in two currencies.
Employer Contributions From FEIE Years Usually Are Not Basis
Under Section 72(f), confirmed in a 1972 IRS revenue ruling, employer contributions that would have been excludable under the FEIE if paid directly to the employee are left out of the investment in the contract. A teacher who excluded her salary for a decade can find that nearly the whole withdrawal is taxable.
That discovery tends to land hard, because it can feel like paying for the same years of work twice.
Some foreign plans work differently, because employer contributions may be taxable in the year they vest. Which rule applies depends on how the plan is set up, so the plan documents matter as much as the payout statement.
Does the 10 Percent Early Withdrawal Tax Apply?
Usually not. Section 72(t) applies the 10 percent additional tax to early withdrawals from qualified retirement plans as defined in Section 4974(c), such as IRAs and 401(k) plans. Most foreign plans fall outside that definition, so the extra US tax generally does not apply.
Can a Foreign Pension Be Moved Into a US IRA?
Generally not without tax. Tax free rollovers into an IRA or 401(k) are limited to eligible US retirement plans, and most foreign plans do not qualify. Moving the money is usually treated as a taxable withdrawal, unless a treaty provision says otherwise.
Do Tax Treaties Change the Answer?
Sometimes. Tax treaty pension rules differ by country. According to the IRS, the pension article in most treaties gives the taxing right to the country of residence, while government pensions and social security payments are generally taxable only by the country that pays them.
The Saving Clause Limits Relief for US Citizens
Most treaties also include a saving clause, which lets each country tax its own citizens and residents as if the treaty did not exist. Each treaty lists exceptions, and only those exceptions help a US citizen. Any treaty benefit that reduces US tax must be disclosed on Form 8833.
Where the Rules Get More Complicated
Some plans do not fit neatly. Australian superannuation funds, for example, can be treated as foreign trusts for US purposes, which brings extra reporting questions.
How Common Foreign Pension Types Compare
Type of income | General US treatment | Where treaties tend to matter | What to watch |
Foreign employer pension | Generally taxable, minus basis | Residence country often taxes | FEIE year contributions usually aren't basis |
Foreign government pension | Generally taxable for citizens | Often taxed by the paying country | Saving clause may limit relief for US citizens |
Foreign social security benefits | Taxed like a foreign pension unless a treaty says otherwise | Some treaties give special treatment | Not treated as US Social Security |
Personal retirement accounts (SIPP, superannuation, provident funds) | Often taxable on growth and withdrawals | Treaty coverage varies widely | Extra reporting can apply |
Using the Foreign Tax Credit to Avoid Double Taxation
When the country of residence taxes the pension, a credit for that tax can usually be claimed on Form 1116. Where the foreign rate is higher than the US rate on that income, the credit can remove most or all of the US tax. Keep the annual tax statement from the pension provider or foreign tax office, because it is the proof of foreign tax paid.
The credit helps less when the foreign country taxes the pension lightly or not at all, or when the two countries tax the money in different years.
For salary, the choice between the exclusion and the credit is a separate decision Jorge covers under strategic tax planning.
Reporting a Foreign Pension on a US Tax Return
Pension payments go on Form 1040, on the pensions and annuities lines (5a and 5b).
Converting Payments Into US Dollars
The IRS generally expects the rate on the date money is received but accepts any posted rate used consistently. Monthly payments are commonly converted at the IRS yearly average rate, while a lump sum is better converted at the payment date rate.
Forms That May Apply to the Plan
Form 8938: the IRS requires reporting an interest in a foreign pension plan once total specified foreign financial assets pass the threshold, valued at fair market value on the last day of the year. Thresholds vary by filing status and residence.
FBAR: whether the retirement account itself belongs on the FBAR depends on the type of account. The bank account receiving the payments is simpler: if all foreign accounts together exceed $10,000 at any point in the year, that account goes on the FBAR.
Jorge handles both reports as part of FBAR and FATCA compliance.
Form 3520: a March 2020 IRS revenue procedure removed this filing for many tax favored foreign retirement trusts, but not the other reports above.
Form 8621: foreign mutual funds inside the plan may trigger PFIC reporting.
Filing Deadlines for Americans Abroad
The IRS gives Americans living abroad an automatic two month extension to file, to June 15. Any tax owed is still due April 15, and interest runs from that date. The FBAR is due April 15 with an automatic extension to October 15.
Catching Up on Unreported Pension Income
Learning that a pension or the account holding it should have been reported years ago can feel alarming. It is a common situation, and there is a defined way back.
The IRS Streamlined Foreign Offshore Procedures let qualifying expats catch up by filing the last three years of tax returns and the last six years of FBARs. The failure must not have been willful, and that is certified under penalty of perjury on Form 14653.
Jorge helps clients through IRS amnesty programs like this one.
Get a Foreign Pension Review Before the First Withdrawal
A pension withdrawal cannot be undone once it is paid, but its tax result can be planned beforehand. A review with Jorge looks at how much of the payment is likely taxable, whether a treaty article applies, how credits for foreign tax will line up, and which forms the plan needs, before the money moves. For teachers, that includes checking which FEIE years overlap with employer contributions, the detail that most often changes the result.
Jorge Rivas, EA works 100 percent remotely with Americans in more than 15 countries through video calls and a secure document portal. He is an IRS Enrolled Agent with unlimited practice rights before the IRS, an IRS e File Authorized Provider, and listed in the IRS Tax Professional Directory, and his practice focuses on international school teachers, missionaries, and expat professionals.
The first step is a free 15 minute consultation with no obligation. Have plan statements, any contribution history, and a list of the years the FEIE was claimed ready, then book through the contact page at jorgerivas.pro, call (803) 467 5815 or (843) 353 0571, or email Jorge.Rivas@RatliffCPAFirm.com.
A pension is the payoff for years of work far from home, and knowing the US tax on it before it is paid out protects that work.
Frequently Asked Questions
Do green card holders follow the same rules as citizens?+
Generally yes, since green card holders are also taxed on worldwide income. Using a treaty to be treated as a resident of another country can count as giving up US tax residency, with consequences of its own.
How are foreign social security benefits taxed in the US?+
The IRS says that, absent a treaty provision, foreign social security is generally taxed like a foreign pension, not like US Social Security. Some treaties change this.
How is a foreign pension lump sum taxed compared with monthly payments?+
The rules are the same, but a lump sum puts the whole taxable amount into one year. That can push the income into a higher bracket and make it harder to match foreign tax credits to the right year.
Does a foreign pension have to be reported if no US tax is owed?+
Yes. The income still goes on the return, and credits or treaty positions are what bring the tax down.
Can foreign pension payments be used to fund an IRA?+
No. The IRS publication on IRA contributions says pension and annuity income is not compensation for IRA purposes, and neither is foreign earned income excluded under the FEIE.
Is state tax owed on a foreign pension?+
It depends on whether the last state of residence still treats you as a resident. Some states continue taxing people who keep a home or other ties there. Educators can find more on state residency in Jorge's guide for international school teachers.
Which records prove basis in a foreign pension?+
Contribution histories, payslips, plan statements, and the US returns filed during those years. Older plans take longer to document, so start early.
Let's Run Your Numbers
The only way to know which is better for you is to model both. Book a free consultation and I'll show you the difference for your country and income.
Schedule Free Consultation →- Jorge I. Rivas, EA
- (803) 467-5815
- Jorge.Rivas@RatliffCPAFirm.com
Related Articles
Late FBAR? How to write a reasonable cause statement
Missed an FBAR? With the Delinquent FBAR procedures gone, a reasonable cause statement carries a late filing. What it must show, an example, and what to avoid.
Does the US–Chile Tax Treaty Change Anything for Americans in Chile?
The US–Chile tax treaty has been in force since December 2023, yet US citizens still file a US return. Here is what it actually changes, and what it does not.
Retiring in Ecuador? US Taxes, IESS, and What the IRS Expects
Dollarization makes Ecuador easy to live in, but not to forget about the IRS. Here is how Ecuador taxes residents, where IESS fits, and what US retirees still have to file.