
Does the US Australia Tax Treaty Eliminate US Taxes for Americans in Australia?
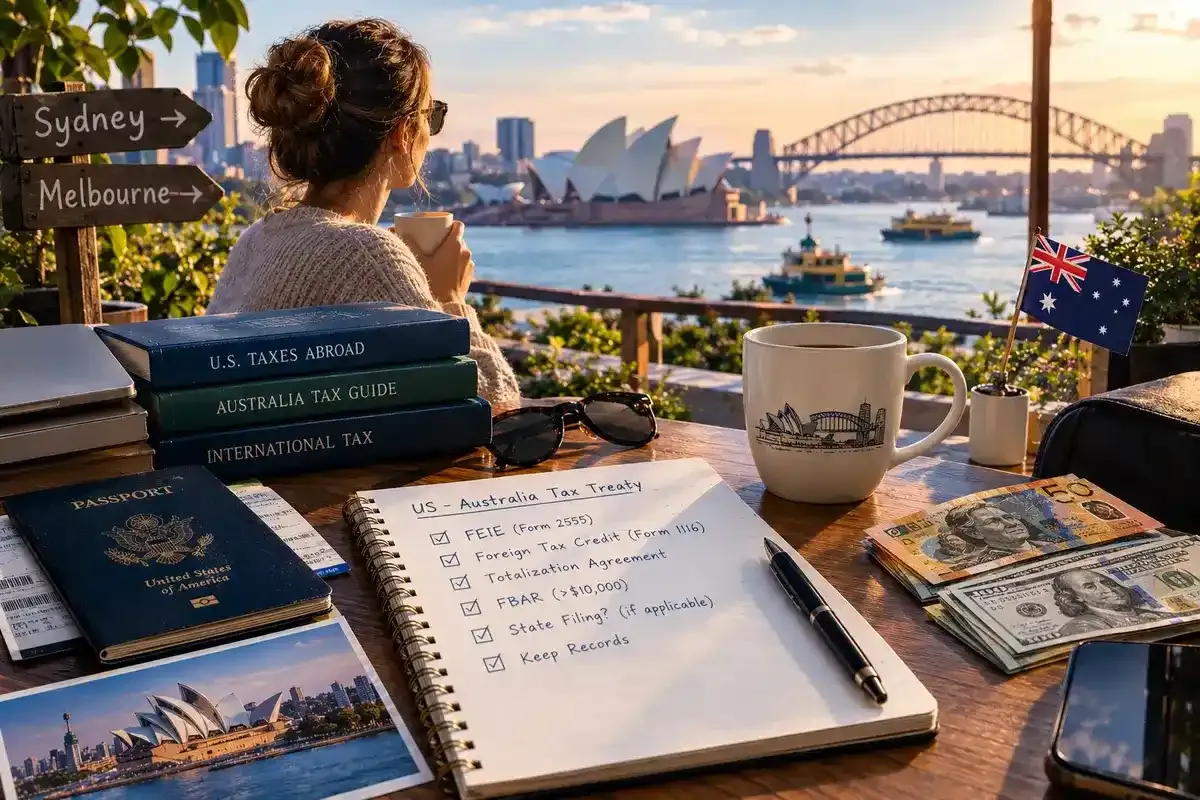
Picture an American teacher in Melbourne who has just read the tax treaty and decided the IRS no longer applies to her. When she speaks with Jorge Rivas, EA, she gets a clear answer: the US Australia tax treaty does not eliminate US taxes, and she still has to file a US return every year. The good news: Australian income tax is generally higher than US tax at most salary levels, so the Australian tax she already pays can offset the US tax on the same income. For most Americans earning a salary in Australia, that means little or no US tax, as long as everything is filed correctly.
Why Doesn't the US Australia Tax Treaty Remove US Taxes?
The reason is a provision called the saving clause. The US taxes its citizens wherever they live, and this clause keeps that right in place. It allows the US to tax its own citizens as if the treaty did not exist.
A few treaty articles are exceptions to this clause, and they hold the real tax treaty benefits for US citizens living in Australia. None of them remove the yearly Form 1040.
What Does the Tax Treaty Between the US and Australia Actually Do?
The treaty exists to prevent double taxation between the two countries. For an individual, it mainly does three things. It decides which country has the first right to tax certain types of income. It caps the tax each country withholds on dividends, interest, and royalties paid across the border. And it sets rules for which country gives a credit for tax paid to the other.
These rules matter most when income crosses the border, such as dividends from a US brokerage account received while living in Sydney.
How Do Americans in Australia End Up Owing Little or No US Tax?
The Foreign Tax Credit does most of the work, not the treaty. Australian salary is reported on the US return, and a credit for the Australian income tax paid on it is claimed on Form 1116. Because Australian rates are usually higher, the credit often covers the full US tax on wages. Credits that can't be used in a given year can generally be carried back one year or forward ten years.
The Foreign Earned Income Exclusion is the other option, but in Australia it is rarely the better choice. The FEIE vs Foreign Tax Credit guide explains the comparison in full.
When Can Americans in Australia Still Owe US Tax?
Even with high Australian rates, a US bill can show up in a few common situations.
Selling shares or property at a gain. Australia currently halves the taxable gain on assets held at least 12 months, but only for Australian residents, and people on temporary visas generally can't use this discount. The US has no matching discount, so the Australian tax may not fully cover the US tax on the gain. The 2026 to 2027 Federal Budget announced changes to this discount from July 1, 2027, so the current rules should be checked before any sale.
Investment income. Foreign tax credits are split into separate categories, mainly general income like wages and passive income like interest and dividends. Extra credits from salary generally can't be used against US tax on investment income.
Low tax years. A partial year of work, a career break, or a year with large deductions in Australia can leave less Australian tax to credit.
Why Does the July to June Tax Year Matter?
The Australian Taxation Office (ATO) uses a July 1 to June 30 financial year, while the US uses the calendar year. So one US return draws income from two Australian financial years. January to June comes from one Australian year, and July to December comes from the next, which may not be finished when the US return is prepared. The timing gap can also leave the first year after a move short of credits, which is one reason the carryover rules above matter.
Australian dollar amounts also have to be converted to US dollars. The IRS publishes yearly average exchange rates that are commonly used for salary, while one time transactions like a property sale are usually converted at the rate on the date they happened.
What Records Are Needed to File From Australia?
Gathering these before the US return is prepared saves the most time:
The ATO income statement and notice of assessment for the Australian financial year ending June 30 of the US tax year.
Payslips for July to December, since the next Australian financial year won't be finished yet.
The highest balance of every Australian bank, brokerage, and super account during the calendar year, for the FBAR.
Super fund annual statements showing contributions and growth.
Dividend statements and any records of shares, funds, or property sold.
Any US income documents, such as a 1099 from a US brokerage account.
What Does the Treaty Cover, and What Doesn't It Cover?
Area | What the treaty does | What the treaty does not do |
US filing | Nothing changes for US citizens | Does not remove the yearly Form 1040 |
Salary | Sets rules to avoid tax on the same income twice | Does not exempt wages; the Foreign Tax Credit does that |
Dividends and interest | Caps withholding between the two countries | Does not change US rules on Australian managed funds |
Super | Has no specific rule for it | Does not let super grow tax deferred like a 401(k) |
Social Security | Nothing; a separate agreement handles it | Does not cover payroll or self employment tax |
Reporting | Treaty positions often need a disclosure form | Does not waive FBAR or FATCA reporting |
Which Australian Accounts and Income Does the Treaty Leave Exposed?
Superannuation
There is no clear IRS guidance on super, and the treaty has no clause treating it like a US retirement plan. It is commonly treated either as an employee benefit trust or as a foreign grantor trust, and the grantor trust approach can make contributions and growth taxable in the US each year.
No approach is completely risk free. What matters is choosing a position that fits the specific fund and applying it consistently, which is how Jorge handles super on every Australia return. The Australia country guide covers super in more depth.
Australian managed funds and ETFs
The IRS generally treats Australian managed funds and ETFs as passive foreign investment companies. That brings higher US tax and a separate Form 8621.
Franked dividends
Franking credits reduce Australian tax on dividends, but a franking credit represents tax the company paid, not tax the shareholder paid. The IRS only allows a credit for foreign tax the taxpayer paid personally, so some US tax on those dividends can remain.
Selling a home in Australia
Australia generally does not tax the sale of a main residence. The US applies its own home sale exclusion with its own limits and measures the gain in US dollars, so exchange rate movements alone can create a US gain.
What Forms Do Americans in Australia File Besides Form 1040?
FBAR (FinCEN 114): required when Australian accounts together exceed 10,000 dollars at any point in the year. Super accounts are generally included. It is filed online with FinCEN, not with the tax return. The FBAR filing guide walks through the process.
Form 8938: required for people living abroad when foreign assets exceed 200,000 dollars on December 31 or 300,000 dollars at any time in the year (400,000 and 600,000 dollars for joint filers).
Form 8833: generally required when a treaty position lowers US tax. Missing it can bring a 1,000 dollar penalty per failure for individuals, even when the treaty position itself is correct.
Does the IRS Know About Australian Bank Accounts?
Usually, yes. Under a FATCA agreement Australia and the US signed on April 28, 2014, Australian banks and other financial institutions report accounts held by US citizens to the ATO, which passes that information to the IRS. Super funds are generally exempt from this bank reporting, but that does not remove the account holder's own duty to include super on the FBAR where required.
Can Americans in Australia Still Contribute to an IRA?
Often, yes, but it depends on the credit or exclusion choice. IRA contributions need earned income that stays on the US return. Salary reported under the Foreign Tax Credit still counts. Salary excluded under the Foreign Earned Income Exclusion does not, so someone who excludes all of their wages generally can't contribute. Contributions to super do not count as IRA contributions.
How Does Filing Work With an Australian Spouse?
A US citizen married to a spouse who is not a US citizen or resident usually files as married filing separately. There is also an option to treat the spouse as a US resident and file jointly. That can lower the tax rate, but it brings the spouse's worldwide income into the US system, so it only makes sense after comparing both ways.
Is a US State Tax Return Still Required?
It depends on the state. Some states keep treating former residents as residents until ties like a home, a driver's license, or voter registration are cut. Moving to Australia does not automatically end state residency, so it is worth confirming before the first return abroad.
What Happens If the June 15 Deadline Is Missed?
Filing Form 4868 by June 15 extends the deadline to October 15. Interest on any unpaid tax still runs from April 15. If no tax is owed after credits, the late filing penalty is usually small or zero, but separate penalties can still apply to late FBAR or Form 8938 filings.
Can Green Card Holders Use the Treaty to Be Taxed Only in Australia?
Sometimes, but it is risky. The treaty's tie breaker rules can treat a green card holder as an Australian resident for treaty purposes. For long term green card holders, the IRS warns that claiming this can count as expatriating, which can trigger the expatriation tax rules.
Does the Treaty Cover Social Security and Self Employment Tax?
No. A separate totalization agreement handles Social Security so the same work isn't taxed by both systems. Self employed Americans in Australia should not assume they are exempt from US self employment tax, since the answer depends on having the right certificate of coverage.
What If US Returns Haven't Been Filed From Australia?
Catching up is usually possible without penalties. If the missed filings were not willful, the IRS Streamlined Foreign Offshore Procedures may apply. The program requires three years of tax returns and six years of FBARs, and for qualifying people living abroad there is no penalty. To qualify, a person generally must have been outside the US for at least 330 full days in one of the last three years, with no US home.
Get a Clear Answer on What the Treaty Means for Your Return
The US Australia tax treaty is only one piece. Your credits, super, investments, and reporting forms decide what you actually owe, and Jorge Rivas, EA reviews them together for Americans across Australia. He is an IRS Enrolled Agent with unlimited practice rights before the IRS, authorized by the IRS to file returns electronically, and listed in the IRS Tax Professional Directory. Everything is handled remotely through video calls and a secure document portal.
Start with a free 15 minute consultation covering which treaty rules apply to you, how your super and accounts should be reported, and what is needed to get compliant, whether you are current or years behind. There is no obligation. Book through the contact page, call (803) 467 5815 or (843) 353 0571, or email Jorge.Rivas@RatliffCPAFirm.com.
Frequently Asked Questions
Do Americans living in Australia still have to file US taxes?+
Yes, if their income is above the filing threshold. Many owe nothing after credits, but the return is still required.
What is the saving clause in a tax treaty?+
It is the part of a treaty that lets the US tax its own citizens as if the treaty did not exist, with a few listed exceptions.
When is Form 8833 required?+
Generally when a treaty position lowers US tax. Some positions are exempt from disclosure, so each one should be checked before filing.
Does the treaty stop double taxation on an Australian salary?+
Not by itself. A credit for the Australian tax paid is what usually cancels the US tax on wages.
Does the treaty cover superannuation?+
No. There is no specific treaty rule and no clear IRS guidance, so a consistent, documented approach matters.
Is the totalization agreement part of the tax treaty?+
No. It is a separate Social Security agreement that affects payroll and self employment tax, not income tax.
Is an Australian accountant enough for US taxes?+
An Australian accountant handles the ATO return. The US return, super reporting, and FBAR follow different rules, so the US side needs its own specialist.
Let's Run Your Numbers
The only way to know which is better for you is to model both. Book a free consultation and I'll show you the difference for your country and income.
Schedule Free Consultation →- Jorge I. Rivas, EA
- (803) 467-5815
- Jorge.Rivas@RatliffCPAFirm.com
Related Articles
Late FBAR? How to write a reasonable cause statement
Missed an FBAR? With the Delinquent FBAR procedures gone, a reasonable cause statement carries a late filing. What it must show, an example, and what to avoid.
Does the US–Chile Tax Treaty Change Anything for Americans in Chile?
The US–Chile tax treaty has been in force since December 2023, yet US citizens still file a US return. Here is what it actually changes, and what it does not.
Retiring in Ecuador? US Taxes, IESS, and What the IRS Expects
Dollarization makes Ecuador easy to live in, but not to forget about the IRS. Here is how Ecuador taxes residents, where IESS fits, and what US retirees still have to file.