
What Counts as Foreign Earned Income for the FEIE? What Qualifies and What Doesn't
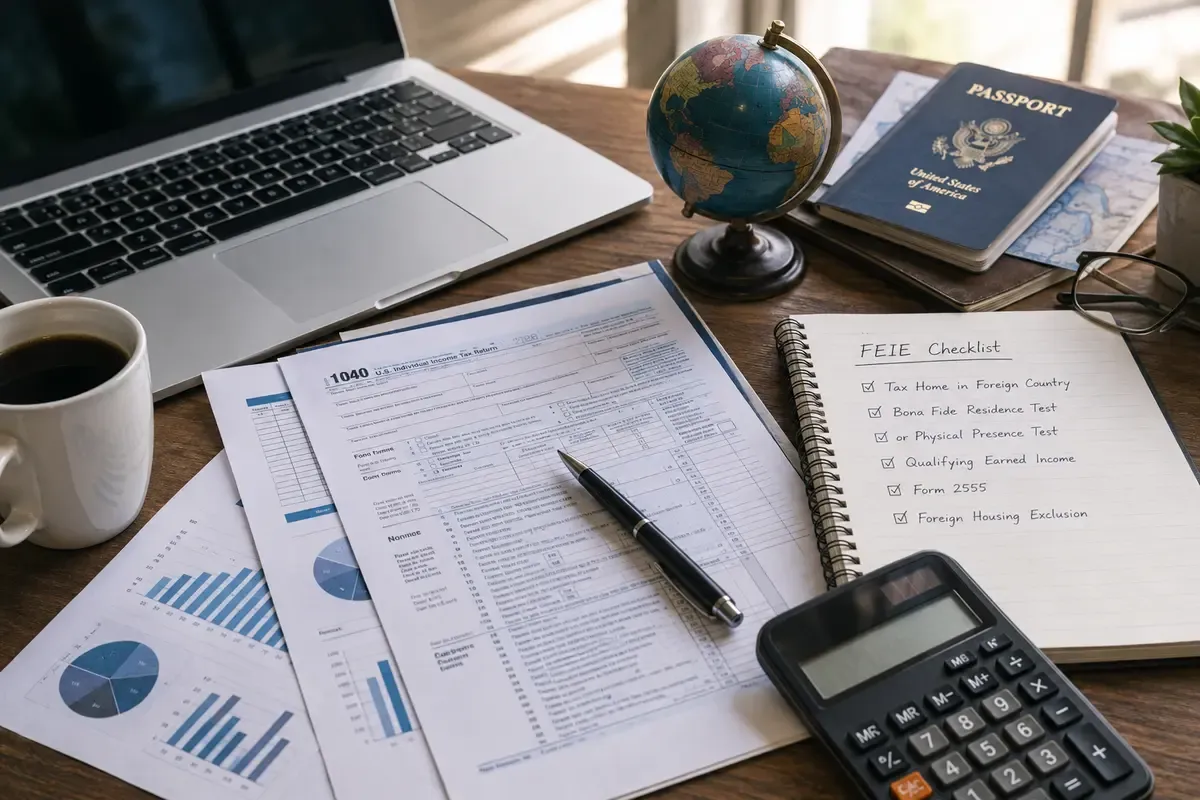
A teacher in Seoul once had three lines on her income summary: a school salary, a housing stipend, and rental income from a condo she still owned back in Ohio. Only two of those three lines had any chance of qualifying for the Foreign Earned Income Exclusion. What qualifies as foreign earned income starts with one question: was the payment compensation for work physically performed while living abroad? But that is only part of the FEIE analysis.
Tax home and whether the Bona Fide Residence Test or Physical Presence Test is met matter too. Salary, wages, and self employment income from active work generally qualify. Rental income, dividends, pensions, and anything paid by the US government do not, no matter where the recipient was living when the payment arrived. Jorge Rivas, EA works through this distinction with clients on a near weekly basis, and it is usually the difference between a return that files cleanly and one that draws an IRS notice.
Why Earned Income and Unearned Income Are Treated So Differently
Congress designed the Foreign Earned Income Exclusion to prevent double taxation on money earned through work while genuinely living outside the United States. It was never meant to shelter investment returns, retirement distributions, or income that would have arrived regardless of location. Every one of the rules for the Foreign Earned Income Exclusion traces back to that single distinction. A payment tied to a service performed is a candidate for exclusion. A payment tied to something owned, a rental unit, a brokerage account, a pension funded years earlier, almost never qualifies, no matter how long someone has lived abroad.
What Actually Qualifies as Foreign Earned Income
Salary, Wages, and Self Employment Income
Regular pay from an employer qualifies, along with commissions, performance bonuses, and allowances paid specifically for working overseas, such as a cost of living adjustment. Self employment income counts too, provided the work was actively performed abroad. One detail that surprises many self employed expats: the FEIE excludes this income from federal income tax, but it does not remove the self employment tax obligation, which is calculated separately. The United States has Totalization Agreements with a number of countries that can eliminate double social security taxation for someone paying into a foreign system, so this is worth checking against the specific country of residence before assuming self employment tax is unavoidable.
Income for International School Teachers
Base salary and most taxable stipends a school reports as compensation generally qualify. Curriculum development pay and summer session income are common gray areas, since schools report these differently from one contract to the next, and the label a school uses does not always match how the IRS classifies the payment.
Income for Missionaries and Ministry Workers
Support raised through a sending organization can qualify as earned income when it functions as compensation for ministry work performed abroad. Whether it actually does depends on how the sending organization structures the support, so each situation needs individual review rather than a blanket assumption.
Income for Consultants, Business Owners, and Remote Workers
Client work performed while physically present in a foreign country generally qualifies, even when the paying client is a US based company. Physical location while doing the work is what controls the outcome, not the billing address on the invoice.
What Kind of Income Does Not Qualify for FEIE?
Investment and Passive Income
Rental income, dividends, interest, capital gains, and royalties not tied to personal work fall outside the exclusion, whether the source is in the United States or the country of residence. Owning an asset and performing paid work are treated as two separate categories under the tax code, and time spent abroad does not change that.
Retirement and Deferred Income
Pension and retirement account distributions do not qualify, even when received while living overseas, since they reflect work performed in an earlier year, often inside the United States. Alimony and Social Security benefits fall under the same reasoning.
Government Wages
Income paid by the US government or any federal agency never qualifies, even when the job is performed entirely overseas. Federal employees stationed abroad commonly assume an overseas posting changes this, and it does not.
Does State Tax Apply the Same Way as the FEIE?
Not necessarily. The exclusion only applies to federal income tax. States vary widely in how they treat income earned abroad, and some states do not recognize the FEIE at all, which means someone can exclude income federally and still owe state tax on the same amount depending on their state of legal residence. Teachers and remote workers who keep a driver's license, property, or voter registration in a state after moving abroad are the most likely to run into this.
Does It Matter Who Pays the Income or Where the Company Is Based?
Not directly. The location where the work was physically performed controls the answer, not the employer's address or the currency of payment. A software engineer living in Lisbon and working for a California based company can still exclude that income, since the work itself happened while she was physically in Portugal. The reverse also holds. Time spent physically working inside the United States, even a short visit home over the holidays, does not count as foreign earned income for those specific days, which is why a travel calendar for the year matters as much as the pay records themselves. Work performed across several countries during the year, rather than just one, still generally qualifies as long as it happened outside the United States, which is common for consultants who split time between two or three postings in the same tax year.
FEIE Qualifying Income Versus Income That Does Not Qualify
Type of Income | Qualifies for FEIE | Notes |
Salary or wages from foreign work | Yes | Must be for work physically performed abroad |
Self employment income | Yes | Excluded from income tax, but not from self employment tax |
Employer housing allowance | Often, separately | Usually handled under the Foreign Housing Exclusion |
Ministry support and stipends | Sometimes | Depends on the sending organization's structure |
Rental income | No | Considered passive, unearned income |
Dividends and interest | No | Investment income, not compensation for work |
Pension and retirement distributions | No | Tied to past work, not current foreign work |
US government wages | No | Excluded by law regardless of location |
How Does the Foreign Housing Exclusion Fit Into This?
Employer provided or reimbursed housing costs are generally treated as compensation, but a portion can often be excluded separately from the FEIE cap under the Foreign Housing Exclusion. The calculation requires a base housing amount tied to a specific city along with IRS provided limits that vary by location, a step frequently skipped by preparers without expat experience. The general housing exclusion limit for 2026 is $39,870, though certain high cost cities carry a higher ceiling set separately by the IRS each year. Keeping the lease, housing allowance letter, and proof of payment on file makes this calculation far easier to substantiate.
What Tests Determine Whether the Income Can Actually Be Excluded?
To claim the FEIE, a taxpayer generally needs qualifying foreign earned income, a tax home in a foreign country, and to satisfy either the Bona Fide Residence Test or the Physical Presence Test. Qualifying income alone is not enough to make it excludable. The Bona Fide Residence Test generally requires being a bona fide resident of a foreign country for an uninterrupted period that includes an entire tax year. Simply living abroad for a year does not automatically establish bona fide residence. The Physical Presence Test instead counts actual days, requiring at least 330 full days abroad within any twelve month window.
Which test fits depends on visa status, how settled the person's life abroad actually is, and how much travel occurred during the year. Using one test in a prior year does not lock someone out of the other test the following year. Either test can apply independently, year by year, which is why keeping a simple travel log matters more than most expats realize. Someone who only qualifies for part of the tax year does not lose the exclusion, but the maximum amount is prorated based on qualifying days divided by the total days in the year, so moving abroad in June rather than January noticeably changes the ceiling on what can be excluded.
What Happens If Only Part of the Income Qualifies?
Most expat tax situations are not all or nothing. A consultant might have client income earned while working abroad, rental income from a property back home, and a dividend from an old brokerage account, all in the same year. Only the client income has any real chance at exclusion. The remainder is taxed under ordinary US rules, though foreign tax credits can often offset double taxation on income also taxed by the country of residence. A mixed income year takes more time to sort through than a straightforward salary case, and the FEIE alone will not simplify a genuinely complicated income picture.
Should the FEIE or the Foreign Tax Credit Be Used Instead?
Qualifying for the FEIE does not automatically mean it is the better choice. The Foreign Tax Credit works differently, offsetting US tax dollar for dollar based on foreign tax already paid, and it often produces a better result in high tax countries such as Germany or the United Kingdom, where the foreign tax paid may exceed what would have been owed to the US anyway. The FEIE tends to work better in low tax or no tax countries such as the UAE, where there is little or no foreign tax to credit against. Some years call for a combination of both on the same return, applying the exclusion to part of the income and the credit to the rest. This decision depends on the specific country, income level, and tax rate involved, and it is one of the most common reasons an expat return needs a specialist rather than off the shelf software.
Two details often get missed in this comparison. First, claiming the FEIE makes a taxpayer ineligible for the Additional Child Tax Credit and the Earned Income Credit for that tax year, even with qualifying children, since excluded income does not count as earned income for either credit. Families with kids abroad sometimes come out ahead using the Foreign Tax Credit instead, once that lost credit is factored in. Second, income excluded under the FEIE does not count as compensation for IRA contribution purposes, which matters for anyone trying to keep retirement contributions on track while living overseas. Neither issue makes the FEIE the wrong choice, but both are worth running through the numbers before deciding.
Switching between the two is also not something to do casually from year to year. The FEIE is an election made by filing Form 2555, and once made it stays in effect for all future years until formally revoked. After revoking it, a taxpayer generally cannot re-elect the FEIE for five tax years without IRS approval, so the choice between the exclusion and the credit is meant to be a durable one rather than something adjusted every season based on which option looks slightly better.
What Happens If the Residency Test Is Not Yet Met When It Is Time to File?
Someone who moved abroad partway through the year may not yet have 330 qualifying days or a full calendar year of bona fide residence by the standard filing deadline. Form 2350 allows a taxpayer in this position to request an extension specifically to meet one of the two tests before filing, rather than filing early and losing the exclusion. This is different from a standard extension and needs to be requested for the right reason, so it is worth flagging to a preparer as soon as it looks like the qualifying period will run past the usual deadline.
What Documentation Should Be Kept to Support the Exclusion?
Pay stubs, an employment contract, or invoices showing the income was tied to work performed abroad
A signed lease, housing allowance letter, or proof of rent payments, when claiming the Foreign Housing Exclusion
A travel calendar or passport stamps showing days spent inside versus outside the United States
Records from the sending organization, for support based ministry income, showing how the support was structured
Sorting foreign salary from rental income, ministry support, or a government paycheck is easiest before filing, not after an IRS notice arrives. A free fifteen minute consultation with Jorge Rivas, EA covers exactly which parts of a specific income mix are likely to qualify for the FEIE and what documentation supports that position. Reach the office at (803) 467-5815, (843) 353-0571, by email at Jorge.Rivas@RatliffCPAFirm.com, or through the contact page on the website to schedule.
Frequently Asked Questions
Does foreign earned income include income paid in a foreign currency?+
Yes. Currency has nothing to do with whether income qualifies. What matters is whether the payment was compensation for work physically performed while living abroad, later converted to US dollars for reporting.
Can I exclude income from a rental property I own overseas?+
Generally, no. Ordinary rental income is not compensation for personal services and typically does not qualify as foreign earned income, even when the property is located overseas. More complex rental or business arrangements may require a closer review.
Does my signing bonus count as foreign earned income?+
It may qualify if the bonus is compensation for services performed while physically abroad. The terms of the bonus and when the related services were performed can matter.
I am a missionary supported entirely by donations. Does that count?+
It can, depending on how the sending organization structures the support and whether it functions as compensation for ministry work performed abroad. This needs individual review, since the structure varies widely between organizations.
Do capital gains from selling stock while living abroad qualify?+
No. Capital gains are investment income, not compensation for work, so they fall outside the exclusion regardless of physical location at the time of the sale.
What if I worked partly in the US and partly abroad during the same year?+
Only the income tied to days physically worked outside the United States can be excluded. This requires allocating income against the actual travel calendar for the year.
Does the FEIE amount change every year?+
Yes. The exclusion cap adjusts annually for inflation, so last year's figure is not necessarily this year's figure. The current year's limit should be confirmed before filing, since relying on an outdated number can throw off the entire calculation.
Let's Run Your Numbers
The only way to know which is better for you is to model both. Book a free consultation and I'll show you the difference for your country and income.
Schedule Free Consultation →- Jorge I. Rivas, EA
- (803) 467-5815
- Jorge.Rivas@RatliffCPAFirm.com
Related Articles
Late FBAR? How to write a reasonable cause statement
Missed an FBAR? With the Delinquent FBAR procedures gone, a reasonable cause statement carries a late filing. What it must show, an example, and what to avoid.
Does the US–Chile Tax Treaty Change Anything for Americans in Chile?
The US–Chile tax treaty has been in force since December 2023, yet US citizens still file a US return. Here is what it actually changes, and what it does not.
Retiring in Ecuador? US Taxes, IESS, and What the IRS Expects
Dollarization makes Ecuador easy to live in, but not to forget about the IRS. Here is how Ecuador taxes residents, where IESS fits, and what US retirees still have to file.