
US Tax Guide for Americans Working in South Korea: Seoul and Busan Edition
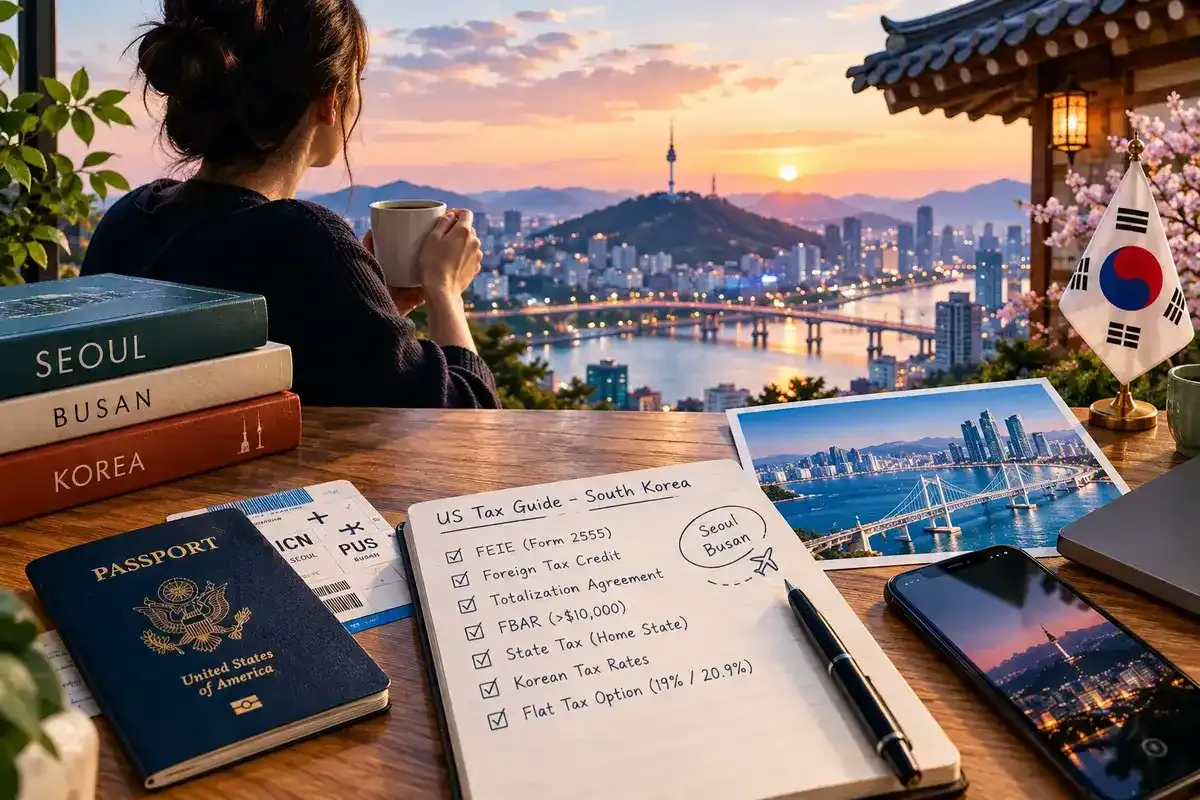
A first year teacher at an international school in Seoul recently opened her first Korean payslip and found a line item she did not recognize: a deduction to the National Pension Service. Her next thought is the one that brings most of Jorge Rivas, EA's clients to him. If Korea is already taxing her, does she still owe the IRS anything back home? The short answer for anyone researching US taxes for Americans working in South Korea, in Seoul or in Busan's smaller expat community, is yes. Every US citizen and green card holder still files a federal return each year, no matter what Korea already withholds, though exclusions, credits, and treaty provisions usually keep the actual US bill low or at zero.
Do I Still Have to File US Taxes While Living in Seoul or Busan?
Yes. The United States taxes citizens on worldwide income no matter where they live. It does not matter if you teach in Gangnam, work in tech in Busan, or run a small consulting practice out of either city. Once income clears the standard filing threshold, the IRS expects a Form 1040 every year, even if every dollar was earned and already taxed in Korea. Americans abroad get an automatic extension to June 15, and can request a further extension to October 15 using Form 4868, but the underlying filing requirement never goes away.
State taxes are often the part people forget. States like California, New York, New Mexico, Virginia, and South Carolina, Jorge's own home state, are known in the industry as sticky states because they make it genuinely difficult to end tax residency, sometimes still taxing former residents who keep a driver license or property back home. Documenting a proper break in domicile is often the difference between owing nothing at the state level and owing thousands.
Why This Is a Job for an Enrolled Agent, Not a General Preparer
An Enrolled Agent is the highest credential the IRS awards, earned through the Special Enrollment Examination, with unlimited practice rights before the IRS at every level. Jorge Rivas, EA is also an IRS e-File Authorized Provider and listed in the IRS Tax Professional Directory, filing electronically for clients across 15 plus countries without requiring an office visit. Details like the totalization gap for private school teachers and the flat tax election below are where Korea specific specialization tends to matter.
How Does the US Korea Tax Treaty Actually Help Me?
The United States and South Korea signed an income tax treaty in 1976, in force since 1979, mainly preventing certain income from being taxed twice and setting residency rules for people who split time between the two countries. The part almost nobody explains clearly is the saving clause, which lets the United States keep taxing its own citizens as if the treaty did not exist. So the treaty helps more with reducing Korean withholding on US source income than with lowering the IRS bill directly. The Foreign Earned Income Exclusion and the Foreign Tax Credit are what actually move the needle, covered next.
FEIE South Korea or Foreign Tax Credit: Which One Saves You More?
Qualifying takes either the Physical Presence Test, requiring 330 full days outside the United States in any twelve month period, or the Bona Fide Residence Test, requiring an uninterrupted full tax year of genuine Korean residence.
The choice between the exclusion and the credit then depends on income, filing status, and how much Korean tax was actually paid. Korea's national income tax alone reaches 45 percent at the top, and with the 10 percent local surtax added, the effective top rate lands near 49.5 percent, well above many low tax countries where the exclusion is the clear winner.
Consideration | Foreign Earned Income Exclusion | Foreign Tax Credit |
Best suited for | Lower and mid income earners, or a lower Korean tax bracket | Higher earners paying substantial Korean income tax |
What it does | Excludes up to the annual limit of foreign earned income from US tax entirely | Credits US tax dollar for dollar against Korean tax already paid |
Effect on retirement contributions | Can complicate IRA contribution eligibility | Generally preserves more flexibility |
Revocation risk | Once revoked, cannot re elect for five years without IRS approval | No similar lock out period |
Which one wins depends on those factors together, not income alone, so the two are worth modeling side by side. They are also not strictly either or: if income runs above the FEIE limit, a stacking rule taxes the excess as if the exclusion never applied, and the credit can then cover that remaining portion. Seoul renters get one more edge too, since Seoul sits among the IRS designated high cost foreign locations, giving a higher housing exclusion cap than the standard limit. Confirm the current year figure against the latest IRS notice before filing.
Can I Elect Korea's Flat Tax Rate as a Foreign Worker?
Here is a detail many guides for Americans in Korea leave out entirely. Korea offers eligible foreign workers a flat rate of 19 percent, 20.9 percent with the local surtax, instead of the progressive brackets. Under a 2023 revision, the election runs for up to 20 years from first working in Korea, up from five, and under current law applies to those beginning by December 31, 2026, worth reconfirming has not since been extended. It applies to employment income, not self employment. For a high earning Seoul employee otherwise in Korea's 40 percent or higher bracket, electing it can lower Korean tax substantially, though it means giving up deductions, a tradeoff that changes whether the Foreign Tax Credit still makes sense.
What About My Korean Bank Account? FBAR South Korea Basics
If combined Korean bank accounts ever exceeded $10,000 at any point during the year, an FBAR filing requirement applies, separate from the tax return. The deadline is April 15, with an automatic extension to October 15 for filers abroad. FATCA reporting kicks in at different, usually higher thresholds. If a deadline is missed without meaning to, the non willful penalty can reach $16,536 per unfiled report, and per the 2023 Bittner v. United States ruling, that applies per report, not per account.
What Happens to My National Pension Service Contributions?
The National Pension Service totalization agreement between the United States and South Korea has been in force since April 2001, meant to stop Americans paying into both US Social Security and the National Pension Service on the same wages. Most employees pay into only one system, usually Korea's, with a certificate of coverage documenting the exemption. Self employed workers follow a residence based rule instead: Korean coverage if living in Korea, US coverage if living in the United States.
The agreement leaves out private school teachers, civil servants, and military personnel. Since most international schools in Seoul and Busan are private, many teachers are not covered the way a corporate employee would be. Future Korean pension distributions can also raise US reporting questions once received, so tracking contributions now matters.
What If I'm a Missionary or Ministry Worker in Korea?
Missionary situations bring their own complexity. Support based income, housing allowances, and how a sending organization structures compensation affect whether SECA applies and how it interacts with the totalization agreement above. Jorge works with ministry workers across several countries because these cases rarely fit standard software or generic advice.
What If I Haven't Filed US Taxes Since Moving to Korea?
If it has been a year or several since a last US filing while living in Korea, the Streamlined Foreign Offshore Procedures let many nonwillful nonfilers catch up on typically three years of returns and six years of FBARs without the usual penalties. Jorge reviews each situation individually, since it is not automatically right for everyone.
Ready to Get Your Korea Filing Handled Correctly?
Whether the open question is FEIE versus the Foreign Tax Credit, Korea's flat tax election, a former home state still owed a return, the National Pension Service gap for teachers, or catching up on missed filings, these are the exact situations Jorge Rivas, EA handles for Americans in Seoul and Busan every filing season. A free fifteen minute consultation, held over video with documents shared through a secure portal, covers what is needed to get and stay compliant. Reach out through the contact page, by phone, or by email to get the Korea filing sorted out properly.
Frequently Asked Questions
Do I owe double tax if Korea already taxed my income?+
Generally no. Between the FEIE, the Foreign Tax Credit, and the tax treaty, most Americans in Korea avoid double taxation, though the mechanics depend on income and source.
Is Korean income tax higher or lower than US tax?+
For higher earners, yes, up to an effective 49.5 percent combined, above US federal rates. That is one reason the Foreign Tax Credit can outperform the exclusion once enough Korean tax has been paid.
Do international school teachers in Korea get special tax treatment?+
There is no separate IRS category for teachers, but housing allowances, summer income, and the totalization agreement's exclusion of private school teachers all shape the return.
What is the National Pension Service and do I have to contribute?+
It is Korea's mandatory pension system. Most employees contribute, though the totalization agreement can exempt certain workers from paying into both systems, with private school teachers an exception.
Can foreign workers really choose a flat tax rate in Korea?+
Yes, eligible foreign employees can elect a flat 19 percent rate, 20.9 percent with the local surtax, for up to 20 years instead of the progressive brackets, though it means giving up deductions and applies to employment income only.
How long does it take to catch up if I haven't filed in years?+
It depends on the number of years and complexity, but most Streamlined filings covering several years of returns and FBARs can be completed within weeks once documents are gathered.
Is expat tax in Seoul handled differently than expat tax in Busan?+
Federal filing rules are the same everywhere in Korea. What differs is employer type, income, and Korean tax paid, which is why the right strategy is evaluated case by case rather than by city.
Let's Run Your Numbers
The only way to know which is better for you is to model both. Book a free consultation and I'll show you the difference for your country and income.
Schedule Free Consultation →- Jorge I. Rivas, EA
- (803) 467-5815
- Jorge.Rivas@RatliffCPAFirm.com
Related Articles
Late FBAR? How to write a reasonable cause statement
Missed an FBAR? With the Delinquent FBAR procedures gone, a reasonable cause statement carries a late filing. What it must show, an example, and what to avoid.
Does the US–Chile Tax Treaty Change Anything for Americans in Chile?
The US–Chile tax treaty has been in force since December 2023, yet US citizens still file a US return. Here is what it actually changes, and what it does not.
Retiring in Ecuador? US Taxes, IESS, and What the IRS Expects
Dollarization makes Ecuador easy to live in, but not to forget about the IRS. Here is how Ecuador taxes residents, where IESS fits, and what US retirees still have to file.